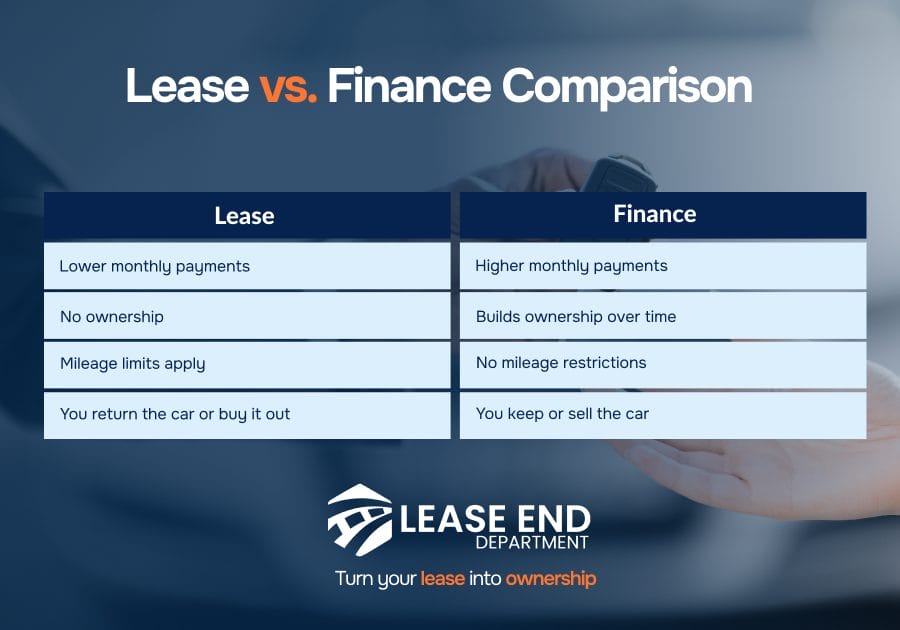
There’s a particular moment many drivers recognize: the transaction screen flashes, the monthly figure looks either breathtaking or unbearable, and suddenly the “obvious” choice feels less obvious. A Chevrolet lease can arrive like a fresh key card to a rotating set of possibilities. Buying, on the other hand, feels like planting a flag—slow, steady, and deeply personal. But what if the real question isn’t lease vs buy? What if it’s whether your current life stage deserves flexibility—or permanence?
This isn’t a debate about numbers alone. It’s a shift in perspective. One option frames your vehicle as a temporary technology companion; the other frames it as an asset with a long memory. Once you see the decision through that lens, the puzzle starts to assemble itself.
The Core Mindset Shift: “Use” Versus “Own”
Leasing tends to treat a car like a curated experience. You’re not just renting transportation; you’re renting time to match your circumstances. Your job changes. Your commute evolves. Your family grows—or shrinks. A lease aligns with those amendments.
Buying is a different philosophy. It assumes continuity. You’re building a relationship with a specific vehicle—miles accumulate, maintenance patterns form, and depreciation becomes a chapter rather than a cliff. This ownership mindset can feel almost ceremonial. It’s not merely practical; it’s psychological.
If you want a simple mental model, try this: leasing optimizes for mobility, buying optimizes for equity. Those aren’t just financial words. They define how you experience the road.
Monthly Payments: The Seductive Clarity of Leasing
Chevrolet lease payments often appear lower than loan payments, and that clarity can be intoxicating. Lower monthly outlay can free cash for insurance upgrades, a second set of wheels, or even simply breathing room. Short sentences are useful here: it feels easier. It looks simpler.
Yet the trick is not the payment—it’s what the payment represents. With leasing, you’re paying for the vehicle’s depreciation during the contract term plus financing charges and fees. You’re essentially paying for the right to use, not the vehicle’s ultimate fate.
Buying, meanwhile, is often higher month-to-month at first. But it comes with a long-term promise: each payment is not only servicing the loan; it’s also accumulating ownership. That distinction—service versus ownership—can be the hinge on which the entire decision swings.
Upfront Costs: When “Due at Signing” Matters
Many people approach leasing like a sprint: get the car now, worry later. That’s reasonable, but the details can be consequential. Lease offers may include due-at-signing items, acquisition fees, taxes, registration, and sometimes refundable or nonrefundable portions. Some leases require less cash at the start; others can feel startling at checkout.
Buying also has upfront obligations. Down payments, lender fees, taxes, and registration stack together. The difference is that buying frontloads investment, while leasing frontloads access.
In practice, the best approach is to ask one question: which plan lets you preserve your financial gravity? In other words, which option keeps your emergency fund from turning into a mirage?
Mileage and Usage: The Hidden Narrative in Your Driving Life
Chevrolet leases typically come with mileage allowances. Exceed them, and your return terms can become a financial boomerang. Lease contracts often specify a per-mile charge over the limit, and those charges can accumulate faster than expected—especially for commuters, rideshare drivers, or road-trip enthusiasts.
Buying usually offers fewer usage constraints. You can rack up miles without triggering a contract penalty. But there’s still a real-world truth: heavier use increases wear and maintenance needs regardless of ownership status.
So the “best” choice depends on your driving autobiography. If your calendar predicts change—new job, new city, new route—leasing can be a well-tailored garment. If your life is stable and you anticipate long-term mileage, buying may fit more naturally.
Condition at Turn-In: The Return That Can Feel Like a Test
One of the quiet differences between leasing and buying is what happens at the end. Leases require a careful return process. Normal wear and tear may be acceptable, but excessive damage—cosmetic or mechanical—can lead to charges. Even minor scrapes can feel like expensive punctuation marks.
Buying doesn’t eliminate wear; it changes how wear is interpreted. The car is yours. Repairs and adjustments become part of your maintenance routine rather than a negotiated outcome between you and the contract.
To avoid unpleasant surprises, treat your leased vehicle like something you’re curating. Gentle driving habits, timely tire rotations, and proactive windshield and paint care can reduce the odds of end-of-term friction.
Depreciation and Residual Value: The Math Behind the Curtain
Leasing is deeply connected to depreciation and the concept of residual value—the estimated value of the Chevrolet at the end of the lease. That residual value influences the lease payment. Higher residual values often mean lower monthly payments, because the vehicle is expected to retain more of its worth.
Buying is also affected by depreciation, but in a different way. You bear the depreciation risk directly. Over time, that can hurt. Or it can become manageable depending on market trends and how the vehicle performs.
Here’s the curiosity spark: sometimes buying can feel like a gamble, but leasing can be a strategic bet on how the market will judge your future return. Understanding that dynamic helps you choose with intention, not impulse.
Technology and Warranty: The Freshness Advantage
Chevrolet vehicles often come with warranty coverage that can reduce the anxiety of unexpected repairs during your ownership horizon. With a lease, many drivers effectively time their contract to align with warranty protection, creating a “comfort bubble.” That bubble can be especially valuable if you prefer predictable expenses.
Buying doesn’t remove warranty support—it just changes the timeline. If you buy and plan to keep the vehicle after warranty ends, you may eventually face repair costs. Some owners counter that by extending coverage or budgeting for maintenance like a disciplined household.
In short: leasing can deliver technological freshness sooner, while buying can deliver total autonomy for a longer span.
Insurance, Taxes, and Fees: Less Drama, More Clarity
Insurance premiums can vary based on vehicle value, leasing terms, and coverage requirements. Leases may require specific coverage limits, and lenders often want comprehensive and collision. Taxes can also be treated differently depending on local rules and how lease payments are structured.
Buying tends to involve different tax and fee timing. You may have sales tax at purchase, financing fees, and possibly other charges. The complexity is real, but the solution is simple: request an itemized estimate for both paths. Compare the total cost of ownership—not just monthly payments.
Credit, Approval, and Flexibility: How Your Profile Shapes the Offer
Leasing often considers creditworthiness and may require a down payment or higher initial payment if your credit profile is less pristine. Buying similarly depends on credit, but the terms and interest rates can diverge in meaningful ways.
Still, the larger question is behavioral: do you want a decision that you can exit smoothly, or one that you can keep building on? Leasing can be a controlled way to change course. Buying can be a way to anchor yourself.
Endgame Plans: What Happens After the Contract or the Loan?
Imagine your future self. If you see yourself changing vehicles frequently, a Chevrolet lease can feel like a well-structured glide path. You return the car, you evaluate new offers, and you upgrade with minimal entanglement.
If you plan to keep a vehicle for years, buying can become the quiet champion. Ownership reduces recurring obligations once the loan is paid off. It can also create a resale story—trading, selling, or driving longer beyond what leasing would allow.
This is where the decision becomes less about today and more about momentum. Which plan supports your preferred pace?
A Balanced Conclusion: Choose the Strategy That Matches Your Life
Chevrolet lease vs buy ultimately comes down to a relationship with time. Leasing often offers lower monthly payments, newer vehicles, and contract-based flexibility—especially appealing when your life is in motion. Buying often offers long-term ownership, fewer mileage constraints, and equity that grows with each payment.
So, don’t just ask which option is cheaper. Ask which option feels less like a compromise. Then verify the numbers, read the terms carefully, and align the decision with your actual driving reality—not an idealized fantasy.
The road ahead is yours either way. The only question is whether you want your Chevrolet to be a chapter that ends on schedule—or a long story you keep returning to.
When you view the choice as a shift in perspective—use versus own, flexibility versus permanence, access versus equity—the answer becomes less mysterious. It’s not about winning the deal. It’s about choosing the vehicle strategy that fits the life you’re actually living.